About Fellwater
An exit for the owner. Not the business.
Fellwater is an independent acquisition firm in the Pacific Northwest. We buy established, profitable businesses from the people who built them, and we own them with a long-term orientation and no predetermined resale date.
How we own
Local where local knowledge matters. Shared where scale helps.
Our starting point is that the business worked before we got there. The name, the people, the customers and the way work gets done are most of what we're paying for, so our instinct is to leave them be. What tends to change is what sits behind the business: an owner who reads the numbers, a bank that returns calls, insurance and purchasing at a size a single company can't get, a bench when someone leaves, and capital for the next truck, the next hire, or the competitor across town.
We're allocators of capital, not caretakers, and we won't pretend nothing ever changes. We don't fix what isn't broken; we do invest where it helps, and when something does change, the owner and the team will know why. The test for what gets shared across the group is simple: does scale create an advantage bigger than the complexity it introduces? Insurance, yes. A new logo, no.
Some owners sell all of it and go. Some sell most of it and keep running it, with a stake in the group. Either way, the business on Monday looks a great deal like the business on Friday.
Founder-led platformsWhat we buy
Established, profitable, and worth keeping.
Roughly $1–3M a year of earnings, in most industries, Pacific Northwest first. The whole company, or most of it with the owner running it.
Usually
- Profitable today. Real, verifiable earnings — roughly $1–3M a year before interest, taxes and depreciation.
- Been around. You've survived a downturn or two.
- Runs without you for a month. A manager, a bench, or systems solid enough that we can find one.
- Customers who come back. Contracts, routes, renewals, a phone that won't stop ringing.
- No customer you can't afford to lose.
- An owner who cares what happens next.
Usually not
- Pre-revenue, or a plan with a logo.
- Earnings that only work because you never paid yourself.
- The business is really you: your license, your hands.
- An auction where the highest number wins regardless of who owns it Monday.
Not sure it fits? Send it. A division, a location, the building, or a business that went to market and didn't sell are all real conversations. Run the cursory check
How we fund a deal
Every deal has a capital structure. Ours is in the LOI.
Fellwater's own equity, partners' equity where a deal calls for it, bank debt sized to what the business can carry — including SBA-backed loans where they fit — and sometimes a note the seller carries, when it makes a deal work and the seller wants it. What's committed and what's subject to a lender's approval sits side by side in the offer, so nobody finds out in month four.
If you're an investor who thinks about businesses the way we do, we'd like to hear from you.
Capital partnersProportions vary by deal. What's committed and what's conditional is named in the LOI.
The people
Meet the team.
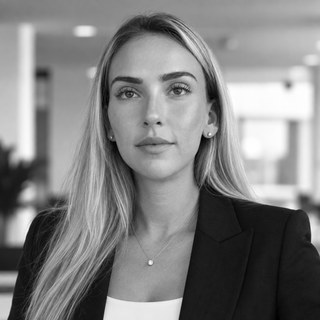
- Certified accountant; two of the Big Four in audit, corporate finance and M&A advisory
- Investment banking at a bulge-bracket bank
- More than four years in private equity
- Leads diligence and structuring — reads the books before we make an offer, not after
Talk to us.
One paragraph: what the business does, roughly what it earns, who runs it, what you'd want after. It reaches the people above.
Prefer to reach us directly? inquiries@fellwater.com · Call or text (206) 895-7474
Who you'll hear from
The person who decides, not an analyst carrying messages up a chain.
- A short call if it might fit
- A written offer after basic financials
- Financials only under an NDA, never through a web form